


Hit by an Uninsured Driver? Know Your Legal Options
 Story by:
Automotives Blog
About one in seven drivers on the road right now has no car insurance at all. According to the Insurance Research Council, when you add in drivers who carry coverage that isn’t enough to pay for a serious wreck, roughly one in three drivers on the road are either uninsured or underinsured. For couples who share a vehicle or plan trips, understanding these coverage gaps can be an important part of protecting their finances when unexpected accidents occur.
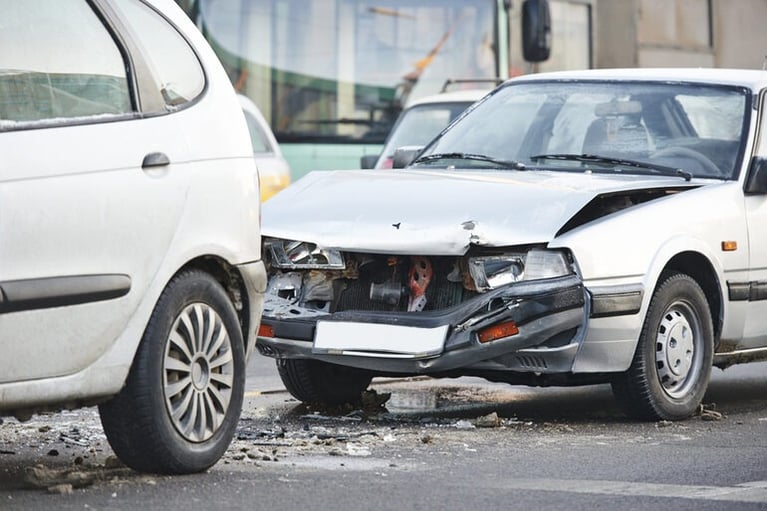
The chances of being involved in a crash with an uninsured motorist are high. In case you had to go through such a situation, dealing with forms and calls can leave more anxious thoughts than the actual accident. If you’re the one without insurance in that crash, even when the other driver caused it, the process gets more complicated still. So what happens if you have no insurance but the other driver was at fault? Let’s look at the legal options you have and what the consequences of driving without insurance are.
Why “At Fault” Doesn’t Mean “Paid”
Most people assume that if the accident wasn’t their fault, the other driver’s insurance just handles it. That’s true when the other driver has insurance. Real problems arise when the other driver’s insurance is not enough to cover the damages. Legally, an uninsured at-fault driver still owes you money. They caused the wreck, so they’re still responsible for your medical bills and your car repairs. The catch is that “legally responsible” and “able to pay” are two very different things. A judgment against someone with no insurance and no assets is often just a piece of paper.
You can win the case but still get nothing out of it. This situation explains precisely why underinsured motorist coverage appears in auto insurance policies frequently. This coverage steps in to pay you directly when the at-fault driver can’t. Instead of pursuing someone with nothing to offer, you’re working with your insurance company, to which you’ve already paid premiums. A Mississippi car accident lawyer can walk you through what your specific policy actually covers, since “uninsured motorist coverage” on paper and uninsured motorist coverage that pays out in practice aren’t always the same thing. Either way, the paperwork is a lot less intimidating once you know which questions to ask.
The State You’re In Changes Everything
Whether you have UM coverage and how much it protects you depends heavily on where you live. For example, more than 1 in 4 drivers in Mississippi are uninsured, according to that same Insurance Research Council data. This figure alone doesn’t make UM coverage mandatory. Under Mississippi law, it requires insurers to offer uninsured motorist coverage on every policy, but drivers are allowed to reject it in writing. Many people do, usually to shave a few dollars off their premium, without realizing what they’re giving up. If you’re shopping for a policy in Jackson or anywhere else in the state, that rejection form is worth reading twice before you sign it. Anyone dealing with the aftermath of a wreck there, especially one involving an uninsured driver, is often better off talking to a car accident lawyer before accepting whatever number an adjuster first offers.
North Carolina takes a different approach. State law requires every auto policy issued there to include UM and underinsured motorist coverage, and insurers can’t sell you a policy without it. North Carolina also handles fault differently in a way that matters even more. It is one of the few places that still uses the pure contributory negligence doctrine. This law means that the victim cannot ask for compensation if they even have 1% of fault. The majority of states use the more nuanced comparative negligence, which merely apportions fault without completely abolishing one’s right to recovery. Mississippi, for what it’s worth, uses a pure comparative system, so a driver found mostly at fault there can still collect for the portion that wasn’t their fault. These examples show how two states can have two very different sets of liability rules.
What the Coverage Gap Actually Costs
It would be better if the applicable amount were presented in terms of actual monetary value rather than an abstract range. When a collision of any type that leads to minor injuries happens, the driver without coverage expects to spend anywhere between $3,000 and $15,000. If it is a moderate injury that the plaintiff will recover from over the next six months, the treating doctor could cover the cost, which would be between $15,000 and $60,000. Under such a situation, the person would incur surgery costs, adding to the $75,000 or more. Those figures aren’t a guarantee of what any one case is worth. Every accident and every policy is different.
A lawyer or insurance adjuster looking at your specific medical records and lost wages will land on a very different number than a generic table ever could. The table shows the minimum liability limits in most states and the amount an at-fault driver must carry while driving in cities. These figures fall well below what a serious injury actually costs. When that driver has no coverage at all, the entire number shifts onto you unless UM coverage is there to absorb it, creating an added financial strain for couples already dealing with the practical consequences of an accident.
What Actually Happens After the Crash
The steps that follow an accident involving an uninsured driver include seeking medical assistance and tracking the entire incident. The crash victim should also obtain a copy of the police report. Instead of filing against the other driver’s liability insurance, you file a UM claim with your own insurance carrier. That sounds simple, but keep in mind that your own insurance company has a financial interest in paying you as little as possible. It’s an odd position to be in, and it’s part of why these claims tend to take longer and involve more back-and-forth than a standard liability claim. Documentation is especially important here. You’ll typically need to show that the other driver actually caused the crash and that they were, in fact, uninsured.
The report could be sent through the police report or through a formal request to the DMV. This action will check the other driver’s insurer to confirm that no active policy exists. Skipping that step, or assuming the claim will just sort itself out, is a common way people end up settling for far less than their losses actually total. There’s also a timing issue people don’t think about until it’s too late. Every state puts a clock on how long you have to file, and your own insurance policy may set an even shorter internal deadline for reporting a UM claim than the state’s general statute of limitations allows. Waiting a few months “to see how the medical bills shake out” can quietly cost you the claim entirely.
If You Weren’t Insured Yourself
Being uninsured yourself doesn’t erase the other driver’s fault. If they ran the light or rear-ended you, they’re still on the hook for what they caused, regardless of your own coverage status. The aspect that changes is the method of collecting the settlement amount. Without your own UM coverage, you may have to pursue the at-fault driver directly, which is much harder if they have limited assets. Being in an accident with a driver who is not insured or underinsured can be a major setback.
Obviously, there would be some difference compared to a situation where the involved parties are properly insured. Know whether your state will wipe out your claim over a small fault percentage. One should also be familiar with the time limit involved in filing a claim. Keep in mind that the time limit begins on the day of the crash, not the day you finally get around to dealing with it, a detail that can matter when partners are helping each other manage the aftermath of an unexpected accident.


Comments 0
No Readers' Pick yet.